CG Invites Refutes Reports of Financial Pressure…Considers Asset Sales and Fundraising in H1 Next Year
English translation of the original Korean report. Images and source documents may contain Korean text.
The Invites Ecosystem, led by Shin Yong-kyu, Chairman of the CG Invites Board of Directors, acknowledged a temporary liquidity burden in response to reports of financial pressure and presented asset sales and additional fundraising measures. However, its affiliate Invites BioCore postponed the payment of unpaid dividends of 1.06 billion won for another year, and it was also revealed in a public disclosure that it provided shares held by an affiliate as collateral to guarantee hospital debt.
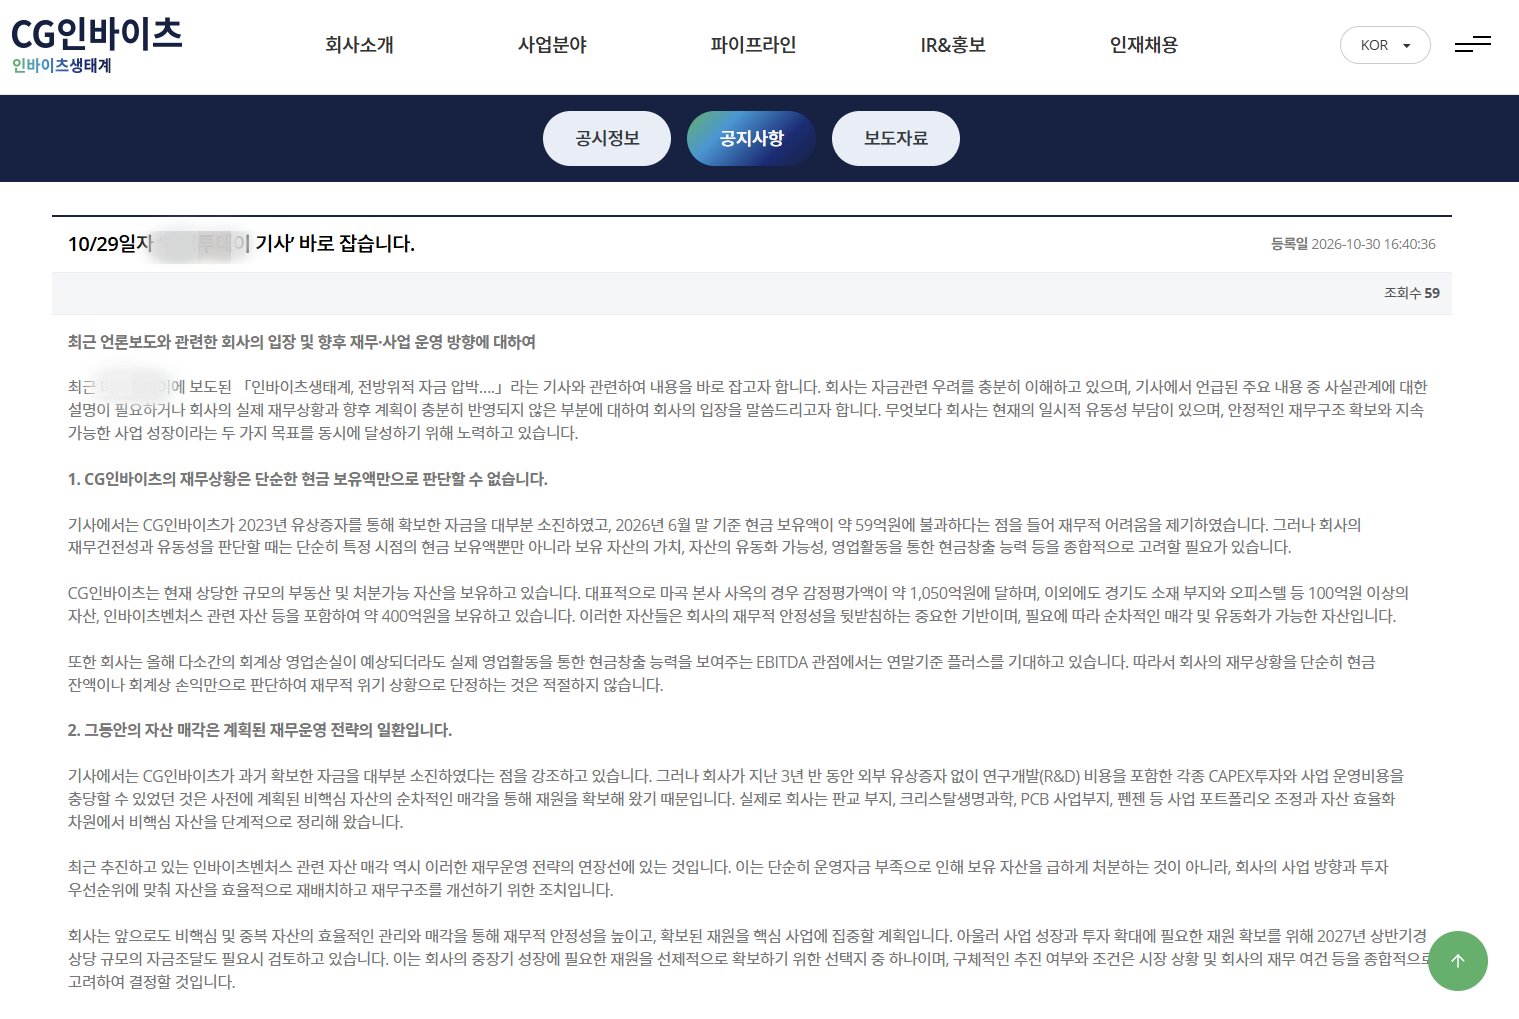
According to the Financial Supervisory Service’s electronic disclosure and the company’s website on the 2nd, Lee Ho-young, CEO of CG Invites, issued a statement on the 30th of last month regarding reports of financial pressure in the name of the Head of Management Support Division of the Invites Ecosystem.
The Invites Ecosystem is a corporate group that includes CG Invites, Invites BioCore, Health Connect, and others. As of the large shareholding report on the 26th of last month, CG Invites’ largest shareholder was Newlake Invites Investment, holding a 27.86% stake. Invites BioCore exercises control over this company through Invites Investment, and Chairman Shin also serves as the CEO of Invites Genomics, the largest shareholder of Invites BioCore.
The core of the company’s proposed countermeasures is to sell assets and convert them into cash. The company explained that the appraised value of its Magok headquarters building is approximately 105 billion won, and that real estate and disposable assets support its financial stability.
It also explained that the ongoing sale of assets related to Invites Ventures is a planned financial strategy. It stated that a substantial amount of fundraising in the first half of 2027 would also be considered if necessary, but the decision on whether to proceed and under what conditions would depend on market conditions and financial circumstances.
A decrease in cash and an improvement in operating cash flow appear together in disclosures. CG Invites’ consolidated cash and cash equivalents as of the end of June this year were 5.94 billion won, a decrease of approximately 5.65 billion won from 11.58 billion won at the end of last year. The decrease rate is 48.8%.
Although the consolidated operating loss in the first half of this year was 11.97 billion won, the net cash outflow from operating activities was 550 million won. This outflow significantly decreased compared to 14.61 billion won in the same period last year. This is why an accounting loss should not be interpreted as the same amount of cash depletion.
The company expected EBITDA (earnings before interest, taxes, depreciation, and amortization) to record a positive figure by year-end. However, EBITDA is a different indicator from actual cash flow, which reflects all investment expenditures and changes in working capital.
■ BioCore Dividend of 1.06 Billion Won Postponed Again…Shares Pledged as Collateral for Hospital Debt
Recent disclosures by Invites BioCore show ongoing adjustments to payment schedules. On the 29th of last month, the company changed the scheduled payment date for the remaining preferred stock dividends of 1,059,999,820 won from October 31 this year to October 31 next year. The reason given was consultation with investors.
This dividend is the remaining amount out of a total of 1,259,999,820 won decided by the board of directors in August 2024. Only 200 million won was paid in April last year, and in April this year, the payment date for the remaining amount was also postponed to the end of October. This time, it has been delayed by another year.
The provision of collateral for hospital debt is also separately confirmed. According to the large shareholding report on the 26th of last month, Invites Investment provided 480,000 shares of CG Invites stock it held as collateral to H+ Yangji Hospital, Seoul Hyocheon Medical Foundation, on the 19th of the same month. The purpose is to guarantee debt between Invites BioCore and the hospital, and the collateral agreement period is until January 31 next year. The disclosure specified that there is no separate loan amount under this agreement.
Regarding the previously reported provisional attachment of assets by the medical foundation, the company explained that it was a temporary issue during the payment process and has since been lifted. It stated that BioCore’s cash and cash equivalents are approximately 4.3 billion won based on internal calculations. This is the company’s explanation, which differs from the publicly disclosed figures and reference point at the end of last year.
The publicly disclosed maturity date for the 21 billion won convertible bonds issued by BioCore is December 5 this year. The holder of all the bonds is Newlake Alliance The Healthcare, which is higher in the ownership structure. The conversion price stated in the notes to the business report is 9,548 won, adjusted from the initial 13,640 won.
Regarding the acquisition of Health Connect, the company explained that it was a strategic decision considering the potential for technology and business synergy. It stated that costs and losses after the acquisition would be reduced through management efficiency improvements and business structure optimization.
The company stated that it would continue with non-core asset sales and a profit-oriented business restructuring. It also stated its intention to connect digital healthcare collaborations with overseas medical institutions to actual sales and profits.